

While the global stock market is on fire the results on the Mexican market are more muted. While long term I think Mexico is a clear beneficiary from the tensions between the US and China. Short term Mexico is hurt by the global trade war.
I still like the richer Mexicans as a theme. Given exposure to the trade war and it usually more cyclical nature I’m even less inclined than before to invest in car parts or chemical companies.
My research in the Mexican stocks so far has resulted in 3 positions:
The Mexican government released a plan in Q4 2024 to build over 1 mln. socially financed homes or 170.000 a year. The Mexican government has a long history of influencing the real estate market. Given the uncertainty around trade and the lack of home building in recent years I think this plan makes sense. It is the reason, in combination with a very low valuation I have a position in Consorcio Ara.
My only worry is their continued investment in more land which delivers a lower return than I like.

My largest position is in Promotora y Operadora de Infraestructura L shares. This large owner of highway concessions does benefit from more trafic. All the concessions have significant time left and the company is investing in new ones. EPS for 2024 was $21.39 MXN on a share price of $181 MXN.
Recently Pinfral sold it’s Mexican port. I think they got a good price. Just wondering what they will do with all the cash, given they already have net cash balance sheet.
Stock is up since I wrote about it, but so are earnings and I have increased my exposure recently. The value of Pinfra shares should in my opinion benefit from lower interest rates.

Last and smallest position I have in Mexico is Banco del Bajio. A Mexican bank focused on commerical loans. The stock performance has not been great. This is mostly caused by lower interest rates, but also by some credit reservations. Mostly though the problem has been valuation. I thought the stock was cheap at 6.6 times earnings. Now it trades at 4.8 times earnings. The position in Banco del Bajio was always a bit of a hedge that helped with higher interest rates in Mexico.
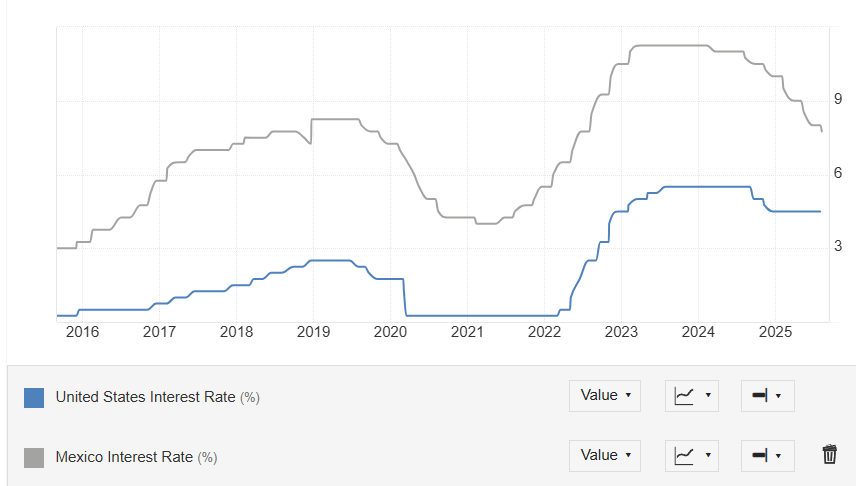
The current differential with US rates is small compared to history. In my first post I had 3 scenario’s with ROE staying at 24%, going to 15% and going to 12%.
For the first half of 2025 ROE was 20.6%. The market is clearly thinking this will decline further given that the stock has a $50B MXN market cap
I do like the stock here at a $50B MXN market cap and and $39B of equity. Even at a 15% ROE Banco del Bajio still trades at an attractive 8.5 times earnings.

Having covered my existing Mexican position I will cover some uncovered Mexican stocks.
PLANIGRUPO LATAM
Developer and owner of shopping centres. With ownership of 36 shopping centres and 1 under management. Making it one of the largest owners of shopping centres in Mexico. Q4 2024 Planigrupo acquired Grupo Acoste Verde increasing the number of shopping malls from 27 to 36.
The value of Planigrupo’s shopping centres is valued at $15B MXN and $1B MXN for the 40% stake in shopping centre Macroplaza Insurgentes. Net debt is $6B MXN.
There is $1.4B in deferred taxes which leaves $9B in equity. In that light a market cap of $5.3B MXN looks quite attractive. Is it really though? lets look at how much these shopping centres are delivering to shareholders.
From January till June 2025 the company earned $476M MXN. This looks great compared to the market cap. Problem is though that $413M MXN of that was revaluation on the properties. This means true cash flow is not great. The company will benefit from lower interest rates though.
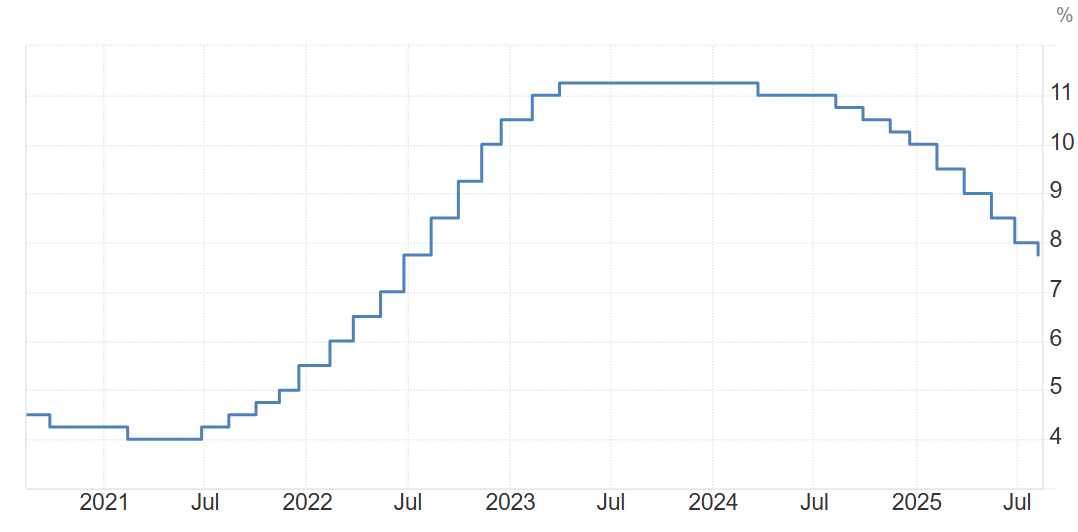
Given the low earnings, there are more interesting plays to benefit from lower Mexican interest rates. One of those places might be Grupo Mexico, which owns 95% of Planigrupo. Grupo Mexico performed well since I wrote about it last year. It might still be an attractive stock! I’m still looking at it.
Grupo Mexico: buying the best copper company in the world at a discount

Continuing on my way to cover all Mexican stocks I found Grupo Mexico. This company deserves an article on its own. As a bonus I will separately discuss GMXT in which Grupo Mexico owns a 70% stake.
Grupo Pochteca
$835M MXN market cap.
Grupo Pochteca, S. A. B. de C. V., is a Mexican business conglomerate with an international presence, specializing in the responsible marketing and distribution of industrial supplies. It serves more than 40 industrial sectors, including key areas of the economy—the automotive industry, oil exploration and drilling, metalworking, food, personal and home care, paints and coatings, water treatment, cleaning and sanitizing, mining, construction, and a broad spectrum of other industries in Mexico, Central and South America.
Pochteca managed to lose money in both 2024 (-$241M MXN) and 2023 (-$282M MXN). Net tangible book value is $204M MXN.
Not sure what their competitive advantage is but I don’t like the losses in recent years. Pass
GRUPO POSADAS
Market cap $14B MXN
Posadas is the leading hotel operator in Mexico that owns, leases, franchises and manages more than 180 hotels and 29,000 rooms in Mexico and the Caribbean, under its 9 brands, achieving efficient centralized management and high-level economy of scale. The pipeline includes agreements to operate 22 new hotels with 3,711 over the next three years.
Not a big fan of hotel companies. Especially not the ones which focus on resorts. They will always have to invest heavily and face global competition from rival resorts.
Posadas has $5B MXN in net debt and last 12 months it had $1.0B in EBITDA. Not interested.
PROCORP
Market cap $336M MXN
Procorp SAB de CV, is a Mexico-based investment company. The Company’s main activities comprise the holding in the capital of small and medium enterprises (SMEs) and the provision of financial and advisory support in their growth projects.
Could not find much and what I found did not make me interested. Pass
PEÑA VERDE
Market cap $3.8B MXN
Pena Verde SAB is a Mexico-based holding company engaged in the insurance and reinsurance sector. The Company carries out is activities through its subsidiaries General de Seguros SAB (GenSeg), Reaseguradora Patria SAB and Patria Corporate Member Ltd, which are mainly involved in the provision of a variety of direct life, health, casualty, third party liability, agricultural, fire, automotive, aircraft and boats insurance and reinsurance policies, among others.
This seems quite a lot variety for a insurance company of this size.
Peña Verde is growing its premium from $10.9B MXN in 2021 to $19.9B MXN LTM.
Equity is $5.8B MXN at Q2 2025.
Profit in 2024 was $1.3B MXN. For the first 6 months of 2025 it was $340M MXN.
These look like very interesting numbers on the face of it.
The combined ratio for Pena Verde is a bit higher and less stable than I like it to be. I do think a significant reason for the higher combined ratio is the higher interest rate in Mexico if you can earn significantly on safe government bonds you might be willing to offer insurance at a lower rate to benefit from this juicy float.
A higher combined ratio is also natural for reinsurance companies who tend to be active in more competitive fields.
Profits also historically have not been this big. Pena Verde earned $430M MXN in 2021, lost $736M MXN in 2022 and earned $290M MXN in 2023. Average profit for the last 4 years was $318M MXN.
Given the diverse activities and focus on reinsurance I’m not sure how to really judge the quality of the operations.
I do like the valuation compared to book and the recent results though. Not sure I’m 100% comfortable with the strong growth in its books. Growth in insurance can be a double edged sword if you give people insurance for a price below cost this might come back to haunt you years later.
This combined with the low trading volume makes that I’m not interested enough to find a way to trade this stock
QUÁLITAS CONTROLADORA
Market cap $69B MXN
QUÁLITAS CONTROLADORA is the leading auto insurance company in Mexico, with international presence in the United States, El Salvador, Costa Rica, Colombia and Peru.
Looks like a high quality company. Profits have been increasing in the last couple of years from $3.7B MXN in 2021 to $5.1B in 2024. Revenue increased from $40B MXN to $73B MXN. H1 2025 has been great as well with premiums up $4B MXN and profits increasing from $2.6B MXN to $3.6B MXN.
Company has a decent dividend history with a $8 MXN dividend per share in 2024 for a 4.7% yield.
My big worry with this stock is though that the combined ratio is quite low at the moment for both Qualitas Controloadora and the industry.
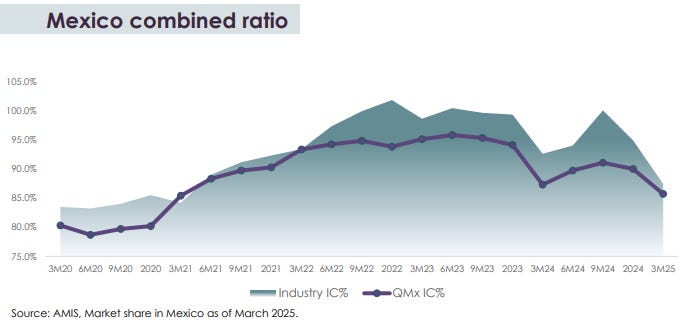
You are paying $69B MXN in market cap for a stock with only $24B MXN in equity. This is okay if the company can keep growing and earning 20% on capital. I’m afraid though that through the cycle the returns might be quite a bit lower. A drawdown to 15% ROE would already be bad news for the stock.
Interesting company though that can benefit from growth in car ownership in Mexico and through the years has created significant shareholder value.
Regional Sab de CV
Market cap $47.7B MXN
Banco Regional de Monterrey S.A., BanRegio, was founded in 1994 as a Banking Institution focused on serving the financial needs of Small and Medium Size Businesses.
Net profit increased from $3.6B MXN in 2021 to $6.5B MXN in 2024.
In a lot of ways Regional is very similar to my position in Banco del Bajio. It focuses primarily on SME customers. Efficiency ratios are similar at 40%. Market cap is similar with $47.7B MXN vs $50B MXN. There are some differences though
Regional has a focus on Monterrey, while Bajio focuses on Bajio.
Regional has
Profit at Regional is $6.5B while Bajio earned $10.7B MXN.
Equity at $34.3B MXN is lower than $39B MXN at Bajio.
Dividend yield at Regional is lower at 4,0% vs 7.1%. Payout ratio seems similar though.
Conclusion Regional looks interesting but I like Bajio slightly better at these valuations.
Conclusion
Nice to write an update on Mexico. Finding some interesting companies for value investors (Planigrupo & Pena Verde). For investors with more of a quality bend Qualitas Controladora is interesting. Banking remains an interesting industry in Mexico for people who can look through the declining interest rates at the moment.
If you have any questions or some great findings yourself do not hesitate to share!
Disclaimer: These are my ideas and not personal investment advice. I might own shares discussed and can sell those shares at all times. I don’t know your financial situation. Do your due diligence and do not blindly follow an article on the internet.
Interested when you arrive at the letter t in tv grupo televisa one of my positions besides femsa,allsea and walmex